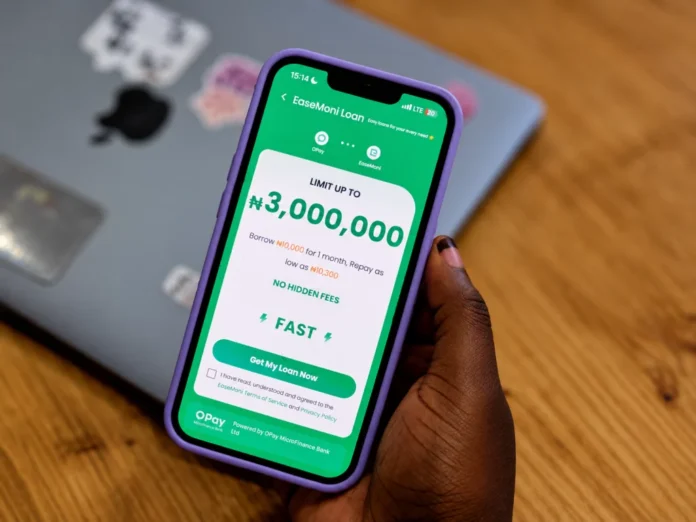
OPay Limited’s expected credit-loss expenses surged to $118.36 million in the first half of 2026, outpacing the growth in its lending income and highlighting the repayment risks behind its rapidly expanding business.
The Nigerian fintech company recorded $467.06 million in revenue during the six months, up 136.5% from $197.48 million in the corresponding period of 2025. Profit after tax climbed to $90.87 million from $21.71 million, according to its registration statement filed with the US Securities and Exchange Commission on October 9.
However, the figures reveal a growing challenge for a company preparing for a proposed US stock market listing: sustaining its earnings as lending becomes its biggest source of revenue.
Loan write-offs jump as lending expands
OPay’s expected credit-loss expenses rose by 210.3% to $118.36 million, while its lending income increased by 167.9% to $236.12 million.
The company also wrote off $113.15 million in loans considered uncollectible during the half-year, representing a 520.5% increase from a year earlier. The amount exceeded the $69.95 million written off throughout 2025.
A further $113.80 million in outstanding loans and interest was overdue as of June 30, equivalent to 27.4% of the $415.33 million owed to OPay.
Although the overdue proportion improved from 34.2% in December 2025, the actual amount awaiting repayment increased from $93.71 million. The lower percentage therefore reflects the faster expansion of the loan book rather than a reduction in the outstanding overdue amount.
Lending overtakes payments as revenue driver
Income from loans issued in Nigeria and lending activities in Indonesia generated approximately 59.5% of OPay’s first-half revenue.
Loans issued directly by the company accounted for $236.12 million, surpassing the $130.55 million generated from payment-related services. Payment revenue nevertheless increased by 86.9% year on year.
OPay’s Nigerian lending operation runs through its licensed microfinance banking subsidiary, which bears the risk of borrowers failing to repay. In Indonesia, the company connects borrowers with third-party lenders and helps service the loans.
New loans issued in Nigeria more than tripled to $927.63 million from $305.12 million in the first half of 2025. The number of unique quarterly borrowers also increased from 3.5 million to 6.7 million.
The expansion helped drive lending income higher, but it also increased the importance of credit assessment and debt recovery to the company’s financial performance.
Changes to lending strategy face a test
OPay said it had tightened consumer lending and shifted towards merchant loans it considered lower risk after temporarily increasing loan sizes and repayment periods for certain borrowers.
The effectiveness of these changes will become clearer as newer loans mature and repayment patterns emerge.
The company’s payment platform provides transaction data that helps it assess borrowers, while lending gives it another way to generate income from its existing customer base. However, the strategy also exposes it to losses when borrowers fail to meet their obligations.
Despite the higher credit costs, OPay’s operating profit increased to $131.24 million from $35.80 million, while its profit after tax more than quadrupled.
The results show that the company remained profitable despite the increase in expected losses and loan write-offs. They do not, however, establish that lending is more profitable than payments after accounting for the respective costs and risks of each business.
With a proposed US listing and a planned secondary listing in Nigeria ahead, OPay’s ability to manage credit losses while maintaining revenue growth will be an important consideration for prospective investors.
