A Nigerian-founded payroll platform is taking aim at a problem that rarely makes headlines but quietly derails the financial lives of millions of remote workers across Africa: the absence of verifiable income records.
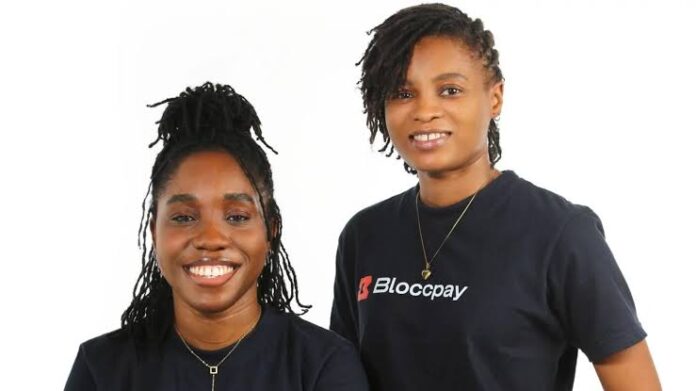
Bloccpay, co-founded by Jennifer Echenim and Ajoke Asunmonu, has built a stablecoin-powered system that combines cross-border payments with bank-grade digital pay slips designed to create what the founders call a “financial identity” for freelancers and contractors.
The Lagos-born startup’s pitch is deceptively simple. Getting paid is only half the battle. The other half is proving you were paid in a format that banks, landlords, and visa officers actually recognise.
That insight emerged from Echenim’s own frustrating experience. After relocating to the United Arab Emirates while working remotely for international clients, she found herself cycling through a “convoluted dance” of friends, stablecoin conversions, and peer-to-peer trades just to access her own salary. The money arrived, eventually. But the records it generated—raw wallet histories and fragmented transfer receipts—were routinely rejected by UAE banks as proof of income.
Brandspur Banking News Desk understands that Bloccpay’s platform now operates across Nigeria, Kenya, Ghana, and South Africa, with payout corridors extending to Uganda and Tanzania. Business customers are concentrated in the United States and United Kingdom.
The company’s technical architecture settles transactions in stablecoins including USDC and USDT across multiple blockchains—Stellar, Base, BSC, and Solana—routing around the high Ethereum fees that made Echenim’s own payments needlessly expensive. Workers can withdraw to bank accounts, crypto wallets, or mobile money depending on their market.
But the real product, according to the founders, is documentation. Every invoice raised and payment received generates a timestamped record showing who paid whom, how much, when, and through what channel. Over time, these accumulate into a verifiable earnings history that can support loan applications, rental agreements, visa petitions, and tax filings.
The operational gap Bloccpay is addressing is stark. Traditional employment automatically produces payslips, tax documents, and recurring salary credits. Independent cross-border work produces nothing equivalent. For Africa’s estimated 15 to 20 million cross-border workers, that documentation deficit can mean the difference between qualifying for a mortgage and being treated as financially invisible.
Harvard Business School research cited by the company puts the cost of moving money across African borders at 8.7% to 12.6% of transaction value—far above the United Nations’ 3% target. Cutting those costs in half could generate between 900,000 and 1.1 million additional remote jobs and add $3 billion to Africa’s remote work exports.
Bloccpay, which began private beta testing in 2023, has processed over $400,000 in gross transaction volume and serves close to 300 users. Gross transaction volume grew sevenfold quarter-on-quarter in Q2 2026, matching the company’s entire 2025 volume by mid-year.
The startup has received a $100,000 grant from the Stellar Community Fund and joined the Circle Alliance Program, a strategic initiative by USDC issuer Circle to support high-potential blockchain startups. It has also participated in the Techstars Founder Catalyst Programme.
Pricing is straightforward: $15 per contractor monthly for payroll processing, a 1% invoicing fee, and a 1% withdrawal fee. Deposits are free.
The founders are candid about the operational complexity of cross-border payments. “Every corridor is its own piece of work,” Echenim said. “Local partners, local settlement times, local failure modes. Nigeria doesn’t work like Kenya”.
That reality has reshaped their expansion thinking. “We used to talk about adding countries,” Echenim said. “Now we talk about corridors, because a country isn’t live until money lands the way people there actually get paid”.
Beyond payroll, Bloccpay’s roadmap includes health insurance, yield products, and other benefits traditionally tied to formal employment—a bid to build what the founders describe as a one-stop financial hub for independent workers.
